

By: Jon Costello
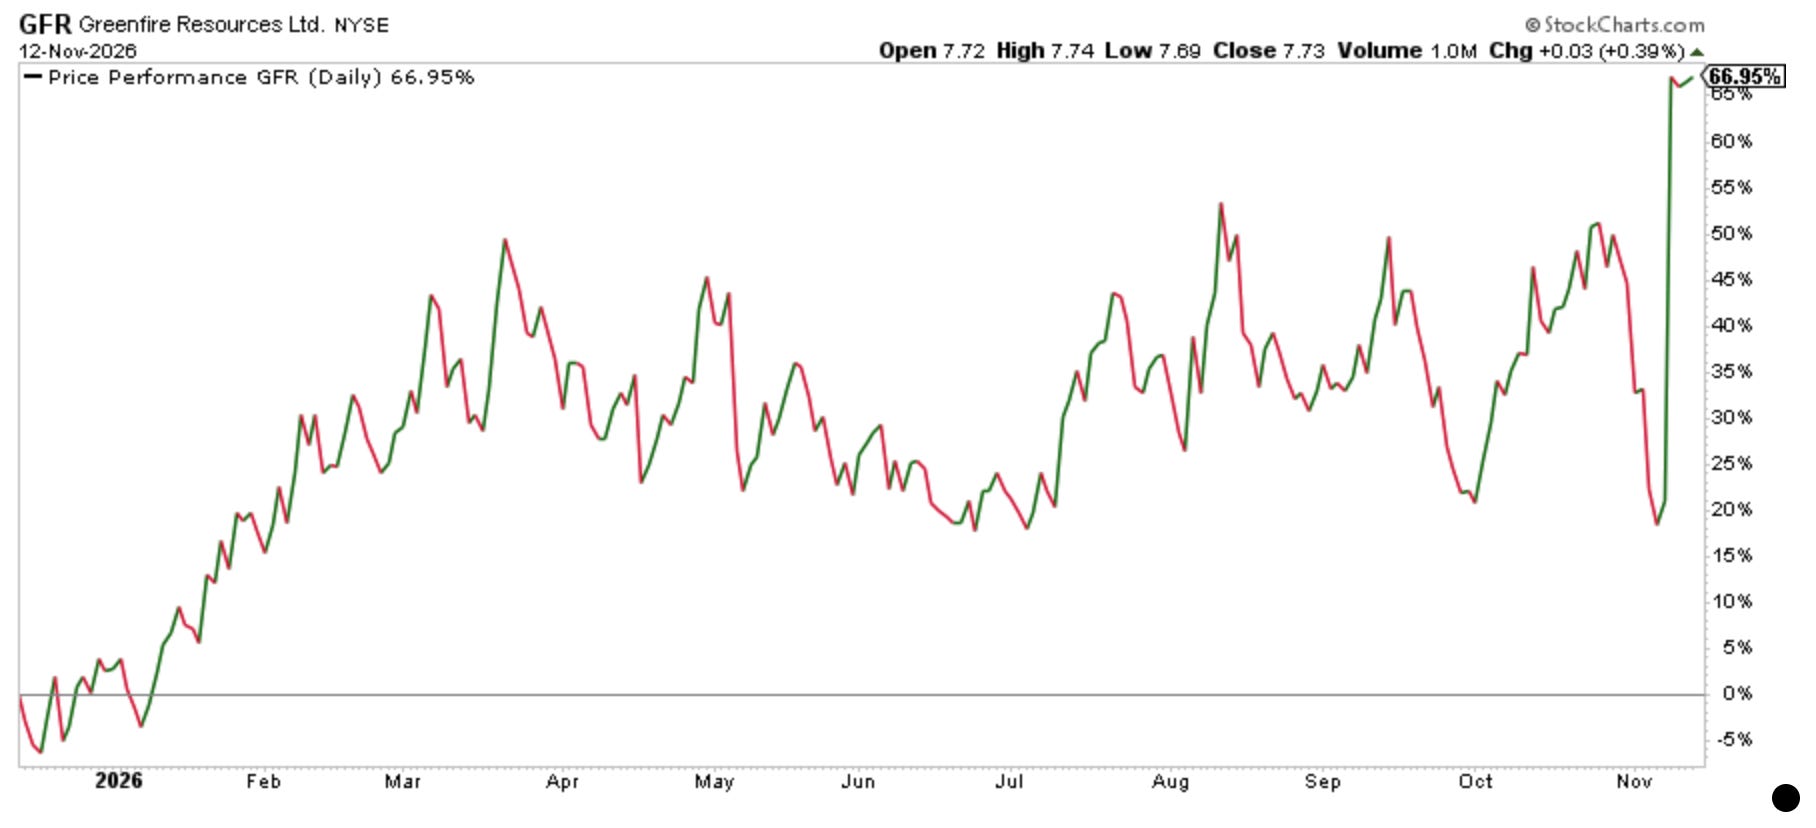
Editor’s Note: On Dec 13, 2025, we published an article on Greenfire Resources calling it one of our favorite energy names. The article is public, and you can read it through the link. Following this acquisition from Strathcona, GFR has returned ~67% since our article.
On November 8, Strathcona Resources (SCR:CA) agreed to acquire Greenfire Resources (GFR). In the proposed deal, each Greenfire shareholder can elect to receive either C$11.00 in cash or 0.25 Strathcona shares for every Greenfire share they own. The deal includes no proration or cap on how much cash or how many shares a Greenfire shareholder can elect. Every Greenfire shareholder will therefore receive their election in full.
I held both Strathcona and Greenfire before the deal. We own Strathcona in the HFIR Energy Income Portfolio, and I’ve recommended Greenfire at various times in the past. At $80 per barrel WTI, I value the combined entity in the range of C$52.50 to C$57.50 per share, well above today’s price of C$37.40.
Despite my valuation, I believe most Greenfire shareholders should opt to receive cash. Unless its shares trade above C$43.68 when the deal closes, the cash offer allows for the purchase of more Strathcona shares than the election to receive shares. Whether the stock trades above that price is dependent on a multitude of uncertainties. And whether Strathcona is worth that much depends substantially on the long-term price of oil.
The Proposed Deal
This deal is likely to close. The Waterous Energy Fund, which owns approximately 57% of Strathcona shares and approximately 72% of Greenfire’s shares, controls both entities. Waterous will vote for the deal. It has signed a support agreement under which it will elect to receive shares in exchange for its Greenfire shares.
But a close isn’t certain. Under Alberta corporate law and Canada’s securities rules, two conditions must be satisfied for a deal like this to close: two-thirds of all votes cast in each meeting must be in favor of the deal, and a majority of the minority votes must also be cast in favor of the deal. This applies to minority shareholders of both Greenfire and Strathcona. Given that the deal incentivizes current Greenfire shareholders to opt for cash, and that many will sell to arbitrageurs who will hold the shares on the record date and are likely to vote for the deal, a closing is highly likely.
So Greenfire shareholders have essentially three options. First, they can sell now in the open market at an approximately sub-1% discount to the C$11 per share cash consideration. The discount mostly reflects the time value of money and demonstrates the market’s confidence in the deal closing. Note that holders of the U.S.-listed shares also have to contend with movements between the U.S. and Canadian dollars, as the cash is paid in Canadian dollars.
Second, Greenfire shareholders can wait until closing and accept the C$11 per share in cash. This is 39% above the pre-deal closing price and less than 1% above the current price. Holders of the U.S.-listed shares will also have to contend with the currency exchange rate.
Third, Greenfire shareholders can elect to receive 0.25 Strathcona shares in exchange for each Greenfire share they own. Holders of Greenfire’s shares listed on the New York Stock Exchange should note that Strathcona trades on the Toronto Stock Exchange and doesn’t intend to list on the New York Stock Exchange, so electing to receive shares would leave them holding a Canadian-listed stock.
